Same money, two markets: what you see when you watch Deribit and Hyperliquid every day

On the night of 21 June, a Sunday, the bitcoin options market on Deribit was the quietest it had been all month. Only $2.75 million of premium changed hands over the whole day. At 20:00 UTC the price started to slide. By 23:50 it was down 1.44 percent, with a low of $63,250, and the public trade feed showed fear waking up: 273 contracts of $60,000 puts bought in the last hour before midnight, insurance against the abyss, about $99,000 of it.
An hour later a ceasefire headline hit. The market jumped, peaked at $65,471 the next afternoon, and everyone who had bought protection at the low was wrong. Except they were not. Four days later bitcoin fell 11 percent and settled the week at $60,455. The protection had been bought at a $60,000 strike. It expired worthless by four hundred and fifty-five dollars.
Right direction, right week, dead position. That is the options market in one story. Before going further, it is worth placing that market next to the one most readers already know.
Options are not new. Crypto options are.
Exchange-traded equity options have existed since the Chicago Board Options Exchange opened in 1973. In 2024 the Options Clearing Corporation cleared about 12 billion contracts, a record year, and nobody argues any more about whether options belong in a serious portfolio. They hedge, they let you take a view on volatility rather than direction, and they fix in advance the most you can lose.
Crypto options are under ten years old as a market. For most of that time they were a curiosity next to spot and perpetual futures. That has changed: on one venue alone, on 10 September, open interest stood near $39 billion. The growth has two engines. Crypto moves more than equities, so an instrument that caps your loss in advance is worth more here than anywhere else. And unlike the equity market, where large trades are negotiated off-screen and reported late, every crypto option trade prints to a public feed with its size, its price and which side initiated. That second point is why this article can exist at all: the big money leaves footprints, and the two venues where it leaves them behave very differently. I spend my mornings reading both.
Two markets, and who sits in each
The first is Deribit, where the large majority of crypto options open interest lives. Coinbase agreed to buy the exchange in 2025, which tells you how the incumbents rate it. In my snapshot of 10 September the bitcoin options book carried 444,205 open contracts, worth about $34.5 billion at that day's price of $77,777. The ether book carried 1.78 million contracts, about $4.4 billion. Call it $39 billion of open options on one venue.
The second is Hyperliquid, an on-chain perpetuals exchange where every position sits in a public wallet. I keep a rolling watchlist of roughly 250 of the largest addresses, of which about 150 hold open positions on any given day. On 9 September at 13:16 UTC those 150 wallets were carrying an aggregate unrealised loss of $131.6 million: longs in profit by $83.6 million, shorts under water by $215.2 million. Sixty-eight wallets were in the green, eighty-two in the red. The pain was concentrated in HYPE, bitcoin and ether, in that order.
The two markets attract the same kind of participant, which is large, patient and impatient in turns. But the instruments punish impatience in opposite ways, and that difference is the most useful thing I know about either market.
The mechanical difference, shown twice in one week
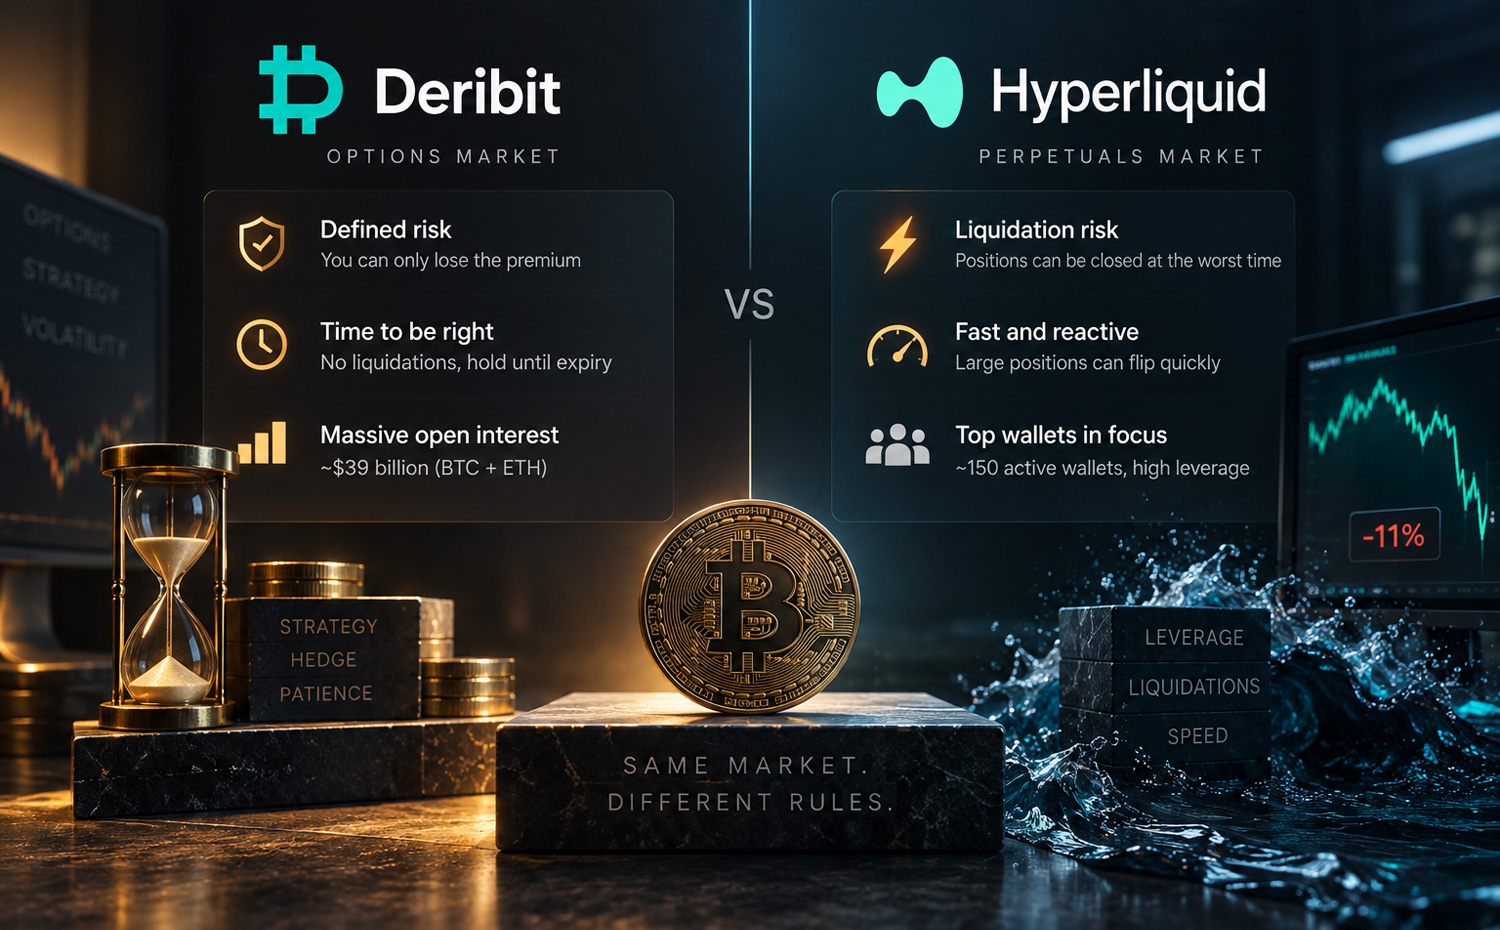
A perpetual future has a liquidation price. Move far enough against a leveraged position and the exchange closes it for you, at the worst possible moment, and your opinion about where price goes next stops mattering.
An option has a premium. If you bought it, the most you can lose is what you paid. There is no margin call, no liquidation, no path dependency. You can be wrong for days and still be right at expiry.
I watched both mechanisms operate on the same week in September.
On Hyperliquid, the top wallets built roughly $130 million of bitcoin longs over one evening. By the next morning the longs were gone and the same wallets were positioned 3.3 to 1 short again. Whether they were stopped out or changed their minds, the public book cannot say. What it does say is that a large directional view lasted less than a day.
On Deribit, on 8 September, a buyer paid for 5,000 contracts of the $81,000 call expiring on Saturday 12 September. Four clips of 1,250 contracts each, at 08:30:37, 08:35:33, 11:21:18 and 11:22:41 UTC, every one lifting the offer. The premium was 31.1 BTC, about $2.44 million at the time. The notional was $392 million. Price then went against the position: bitcoin was $78,407 when the clips printed and $77,777 two days later. Open interest at that strike over those days went 5,060, then 5,047, then 5,032. Almost nothing was unwound.
Same week, same asset, same kind of size. One position was forced to resolve overnight. The other was allowed to sit and wait for its date. That is not a difference in conviction. It is a difference in instrument.
How the professionals use options, and what it costs them
The 8 September buyer was not naive, and the tape shows why. The day before, on 7 September, the same strike saw four paired trades at identical seconds: sell 1,000 contracts of the $81,000 call expiring 9 September, buy 1,000 of the $81,000 call expiring 11 September, repeated four times. That is a calendar spread. The seller collected 7.0 BTC on the near expiry and paid 26.0 BTC for the far one, a net outlay of 19.0 BTC. On 9 September bitcoin settled at $78,102, the near-dated calls expired worthless, and the 7.0 BTC stayed with the seller.
So by Wednesday the structure was: 4,000 calls expiring Friday, 5,000 calls expiring Saturday, both at $81,000, financed partly by a short leg that had already paid off. Total premium at risk was about 50 BTC, near $3.9 million. Breakeven on the Saturday leg was $81,488, which from $76,862 on the Thursday meant a six percent move in two days, while the same options market was pricing a two-day move of 3.3 percent.
This is the professional pattern in miniature: define the loss in advance, finance part of the bet by selling what decays fastest, and size for the outcome rather than the probability. The cost of doing it in size is also visible. The four Tuesday clips were filled at implied volatilities of 40.6, 42.2, 43.9 and 44.1. Minutes after each pair, small lots printed back near 40. The buyer was moving the offer under himself and paying for immediacy. A perpetuals trader pays that cost as funding and slippage. An options trader pays it as vol.
What I cannot see should be said plainly. Deribit does not expose wallets. The four clips are one order by size, timing and identical lots, but that is an inference. The position may be hedged elsewhere, and open interest at a strike is everyone at that strike, not one account. Nothing stops the buyer selling the calls back before Saturday.
Speculators, and the fear premium they pay
The other side of the options market is the retail buyer of short-dated calls and puts: cheap tickets, large notional, almost always worthless at expiry. Their counterparty, over time, is whoever sells them volatility.
I keep a series of what that trade has been worth. In a series that starts in January 2024, taking every week in which the market's fear index sat in its middle range, non-overlapping samples, fifty-one of them: the options market was pricing annualised volatility of 51.9, and the following seven days realised 35.0. In the low-fear range, forty-four samples, the market priced 38.5 and realised 30.6. Fear has been persistently more expensive than what followed it.
That gap is what pays the seller and what the buyer of lottery tickets is up against. It is also why the 8 September buyer's decision to finance the position with a short near-dated leg is not a detail. It is the whole difference between a bet and a structure.
On Hyperliquid the speculator's cost shows up differently. In the exit study I ran on 2,961 half-hourly snapshots over 63 days, the size of a wallet's paper profit or loss did not predict whether it closed the position. What predicted it was time since the wallet last touched anything. Active accounts kept trading, dormant ones kept sleeping, and neither a large gain nor a large loss changed that. Perps let you hold through pain right up to the moment they do not.
The biggest win in the register, with its receipt
Go back to that June week. While the panic buyers were paying for $60,000 puts at the low, somebody had spent the previous nine days assembling the opposite kind of position, at prices far from the market where no chart draws attention.
The fingerprint was on 12 June at 08:09:58 UTC: in one block, sell 500 calls at $75,000 and buy 250 puts at $50,000. Eighty-nine minutes later, the identical block again. On 15 June a series of December $120,000 call sales shrank like an iceberg, 365 lots, then 182, then 109, then 73, about $302,000 collected from people buying the dream. On 18 June, four flat packs of 100 contracts of $55,000 puts bought, and 1,000 calls at $73,000 sold in packs of 250. Then silence for three days.
The assembled position: about 5,300 upside calls sold for $656,000 of premium, about 2,100 downside puts bought for $1.41 million. A net bet against the market of roughly $750,000, financed half by the optimists themselves.
Then the ceasefire news hit against it. The July $55,000 puts repriced to half what had been paid. Half a million dollars of the position was melting, and the feed of 22 June shows the response with measurement precision: nothing. Zero reversal trades.
Four days later the market did what the structure had been built for. Minus 11 percent, to $58,054. Valued at the instruments' last marks on 26 June, the puts were worth $2.47 million against $1.36 million paid, the sold calls could be bought back for $330,000 against $656,000 collected, and a small pack of $50,000 lottery puts burned to zero for a $53,000 loss. Net, an estimated gain of $1.39 million on $751,000 at risk, about 185 percent. The full reconstruction, trade by trade, is the $750,000 bet against the news.
Two limits belong next to that number, and I put them on the page itself. "One player" is a behavioural cluster from seconds, sizes and structures, because Deribit publishes no identities. And the profit is an estimate at marks, not a closed account, because other venues where the same money might have been hedged are invisible.
Now the part that is easy to leave out. That case sits in a register of 1,062 whale constructions I have logged since June, of which 719 have resolved with a measurable result. Three hundred and forty-three of them won. That is 48 percent. Summed at settlement, the register is down about $5.9 million. The smart money, once you count everything it does rather than only the trades that made a good story, is not reliably smart. Its edge, when it has one, is structural: defined risk, financed legs, and the patience to be wrong for a while.
What you can check yourself
Everything above comes from two public sources. Deribit publishes every trade on every instrument, with size, price, implied volatility and which side initiated. Hyperliquid publishes every position in every wallet. You do not need a terminal, only the patience to read the feed instead of the chart.
If you want to see how that reading has held up, the register is public and includes the misses: 1,062 cases and counting.
A journal of decisions, not investment advice. Nothing here is a recommendation to buy, sell, or choose a strike or position size. Reconstructions are from public data; participants are unknown; no claim is made that anyone held non-public information. Past results and their sample sizes do not guarantee future ones. Trading crypto assets and derivatives carries a high risk of loss.
24 July 1979